01Introduction
If you have spent any time around corporate finance, investment pitch sessions, or boardroom discussions, you know the word everyone loves to throw around: EBITDA.
"We are pricing this company at 8x EBITDA."
"Once we hit ₦500 million in EBITDA, our valuation will double."
It sounds clean, polished, and very high-finance. And frankly, if you are running a SaaS business in London or a logistics company in Chicago, where capital markets are deep, inflation is predictable, and you don't wake up to sudden currency fluctuations, EV/EBITDA works as a quick shortcut.
But let us be completely honest with ourselves: if you are running or investing in a mid-market business in Nigeria, Kenya, or anywhere across emerging markets, relying blindly on unadjusted EBITDA is financial playing with fire.
In our environment, EBITDA completely ignores the exact real-world pressures that keep Managing Directors and founders awake at night: foreign exchange illiquidity, working capital bottlenecks, grid instability, and the sheer capital required just to keep factory doors open.
Let us look at why these foreign shortcuts fall short in our market, and how we actually determine true, defensible business value using the three primary valuation approaches, without getting lost in textbook theory.
02The Big Flaw: What EBITDA Misses in Our Market
Consider how business actually operates on the ground in a commercial hub like Lagos, Abuja, or Port Harcourt.
Two manufacturing firms might report the exact same ₦1 Billion EBITDA on paper. But when you inspect their actual operations:
- Company A operates close to an industrial power cluster, receives relatively stable grid electricity, and sources 90% of its raw materials locally in Naira.
- Company B runs 3.5 MW heavy-duty diesel industrial generators round-the-clock, imports 70% of its raw materials in US Dollars, and has cargo constantly delayed at the ports for weeks.
On paper, EBITDA says both companies carry the exact same enterprise value. In reality? Company A generates genuine, spendable cash flow, while Company B is burning cash just to maintain basic infrastructure and cover FX shortfalls.
EBITDA deliberately leaves out Capital Expenditure (CapEx) and Working Capital adjustments. But in Nigeria and similar markets, CapEx is not a luxury or an optional upgrade; it is survival infrastructure, such as diesel gensets, solar arrays, industrial boreholes, and private distribution fleets. When your valuation model skips these costs, it hands you an imaginary number.
03Re-engineering the Three Valuation Pillars for Our Reality
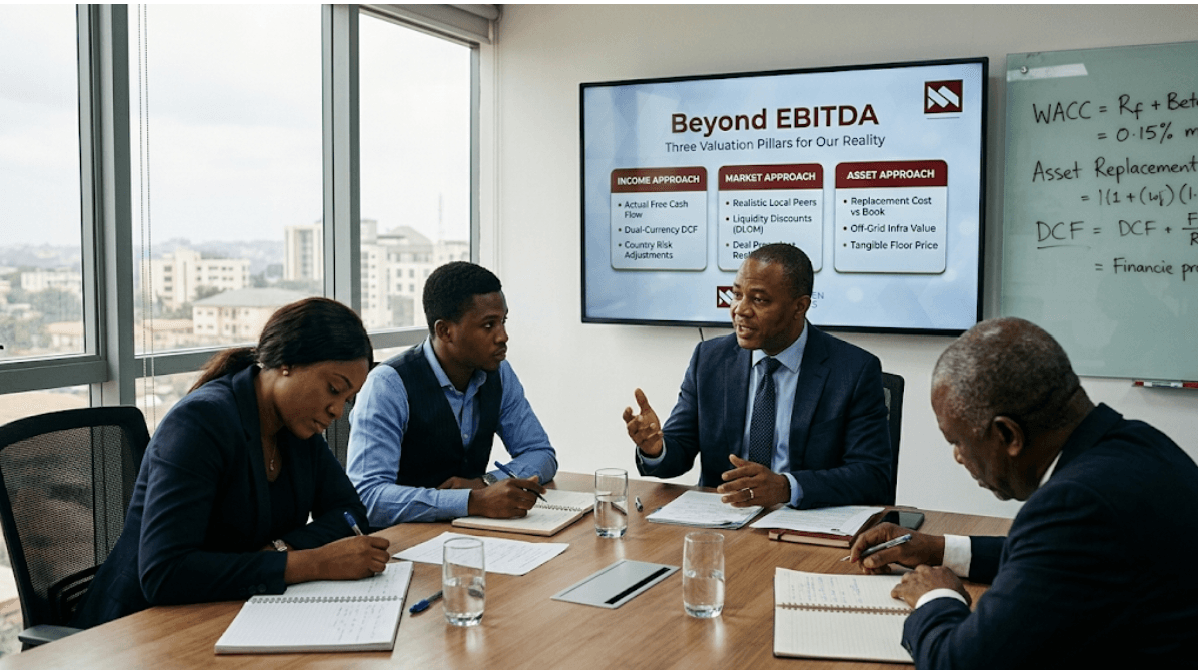
To build a valuation that holds up under intense investor due diligence or bank credit reviews, we have to adjust the standard global playbook. Here is how we approach the three classic valuation pillars at Meck Doramen & Associates:
1. The Income Approach (DCF): Cash is King, but FX Context is Everything
The Discounted Cash Flow (DCF) model remains our preferred foundation because it anchors value directly on Free Cash Flow to Firm (FCFF), which is the actual cash left in the bank after operational expenses, working capital requirements, and essential CapEx are settled.
- Our Field Adjustment: When building DCF models for local enterprises, we do not simply project top-line growth in local currency. We structure dual-currency scenario models. If your raw material inputs are indexed to foreign currency while your revenue is in Naira, we integrate forward-looking FX and inflation curves directly into your cash flow drivers. We also calibrate the Weighted Average Cost of Capital (WACC) to reflect real country risk, size premiums, and key-person exposure.
2. The Market Approach: Finding Comparables That Actually Apply
Relying on transaction multiples sounds straightforward, until you try to find a company that actually matches yours.
- Our Field Adjustment: If you operate a mid-sized beverage processing plant in Abuja or Ibadan, benchmarking your business against a massive listed conglomerate like Nestlé Nigeria or Nigerian Breweries gives a highly skewed result. Private mid-market companies also take significantly longer to trade or exit. We apply realistic Discounts for Lack of Marketability (DLOM), typically between 30% and 40%, to reflect actual exit timelines and liquidity pools in our market.
3. The Asset-Based Approach: Your Valuation Floor
In Western markets, asset-based valuations are often saved for distressed liquidation or property firms. But in emerging economies, this approach serves as a critical valuation anchor.
- Our Field Adjustment: Persistent inflation rapidly renders historical book value useless. An industrial processing plant acquired three years ago could easily cost double or triple to replace today due to currency devaluation, clearing costs, and import tariffs. When evaluating balance sheets, we revalue tangible assets based on current replacement cost, giving proper weight to titled industrial land, captive power installations, processing facilities, and specialized machinery.
04Real Deals, Real Lessons: 4 Recent Case Studies
Let us examine how these valuation principles play out in actual M&A and capital-raising negotiations;
1. Nigeria (Case Study 1): The FMCG Manufacturer & The FX Reality Check
- The Situation: A foreign strategic investor sought a 60% controlling equity stake in an Abuja-based mid-market beverage manufacturer. The founder insisted on an 8.5x EV/EBITDA multiple, pointing to public peer benchmarks across Sub-Saharan Africa.
- The Flaw: While top-line revenue and headline EBITDA appeared strong in Naira terms, 70% of the raw material inputs were imported, exposing operating margins to severe foreign exchange volatility. Moreover, the factory ran 3.5 MW heavy diesel generators due to ongoing grid unreliability, representing a recurring CapEx drain.
- The Resolution: We restructured the valuation using a Dual-Currency DCF Model. Cash flows were evaluated using forward FX assumptions, and CapEx was adjusted to account for generator overhaul and replacement cycles. The final negotiated deal settled at an EV/EBITDA equivalent of 5.2x, protecting the investor from overpayment while safeguarding the founder through a structured earn-out tied to FX pass-through pricing performance.
2. Nigeria (Case Study 2): Valuing a FinTech & Logistics Infrastructure Hybrid
- The Situation: A Lagos-based digital logistics and merchant services platform was raising institutional growth capital. Applying standard international technology revenue multiples (EV/Sales) yielded an initial target valuation of $35 Million.
- The Flaw: Although gross revenue was expanding rapidly, high customer acquisition costs (CAC) and heavy fleet maintenance meant net operating cash flow was negative. Overseas software peers operated under vastly different macroeconomic and capital access conditions
- The Resolution: Deal advisors set aside generic revenue multiples and applied a Sum-of-the-Parts (SOTP) methodology; Proprietary software platform and IP were valued using a Cost-to-Create Asset Approach, Physical fulfillment centers and haulage fleets were valued at Net Realizable Asset Value, Active merchant processing contracts were valued via discounted cash flows at a 28% Cost of Equity.
- The Result: A defensible, realistic $21 Million valuation that institutional investors accepted and successfully funded.
3. Rest of Africa (Kenya): Cold-Chain Agribusiness & Accounting Noise
- The Situation: An East African horticulture grower and cold-chain processor in Kenya was seeking growth equity from an international impact investment fund.
- The Flaw: The business reported depressed EBITDA figures due to recent heavy capital deployment into solar-powered cold storage hubs and non-cash biological asset revaluations (IAS 41). Evaluating the company purely on an EBITDA multiple made an expanding operation look underperforming.
- The Resolution: The advisory team combined an Asset-Based Approach (revaluing solar infrastructure, cold-chain trucks, and titled processing land) with a Multi-Year Free Cash Flow Model. By clearing away short-term accounting distortion and focusing on actual harvest yield trajectories, the business secured an equity valuation 40% higher than an unadjusted EBITDA multiple would have delivered.
4. International / Emerging Markets (India): Proprietary IP vs. Market Multiples
- The Situation: A family-owned industrial components manufacturer in Pune, India, was being acquired by a European engineering group.
- The Flaw: Local transaction averages suggested a conservative 6x EV/EBITDA multiple. However, the business held unique international patents and long-standing supply agreements with global original equipment manufacturers (OEMs).
- The Resolution: Advisors applied the Excess Earnings Method to isolate the cash generated directly by the firm's intellectual property, adding that figure to the factory’s revalued net asset base. The transaction closed at 10.5x EBITDA, demonstrating that a genuine competitive moat overcomes broad market averages when properly quantified.
05Key Action Steps for Business Leaders and Investors
If you are preparing your enterprise for an equity investment, a debt restructuring, an M&A sell-side process, or an internal board review, keep these core principles in mind;
- Avoid Reliance on a Single Formula: Always demand a blended valuation approach, combining an adjusted DCF for growth, a replacement asset evaluation for your floor, and localized deal precedents for validation.
- Normalize Your Financial Statements Early: Clean up discretionary owner expenses, non-recurring FX losses, and heavy off-grid overhead so prospective investors see the true cash-generating power of your underlying business.
- Build Stress-Tested Models: Incorporate realistic macroeconomic scenarios into your financial projections. Evaluate precisely how your margins and debt service coverage react if inflation shifts by 5% or foreign exchange rates adjust by 15%.
06Partnering for True Enterprise Value
Determining the value of a business is not about applying generic formulas in a vacuum; it requires a deep understanding of operational reality, risk factors, and the macroeconomic environment in which your business operates.
At Meck Doramen & Associates, we assist managing directors, business owners, and corporate boards in cutting through financial assumptions to uncover, protect, and maximize genuine enterprise value.
Preparing for a major transaction, capital raise, or corporate valuation review?
Contact our advisory team directly at seniormeck@gmail.com or visit our practice office in Abuja to schedule a private executive consultation.